Appraisal & umpire services · All 14 Vermont counties
Vermont Insurance AppraiserIndependent claim valuation (844) 537-1427
Independent claim appraisal · Statewide

Vermont Insurance Appraiser for claims that came up short

When the carrier agrees the damage is covered but its check will not pay for the repair, Vermont Insurance Appraiser builds an independent, line-by-line valuation and carries it through the appraisal clause in your policy.

  • Your named appraiser
  • Homes, camps, farms & condos
  • All 14 counties

Free claim review

A few details and we will call you back within one business day.

No obligation. Your details stay private.
Ice dam claimsFrozen pipe burstsSnow load collapseFlash flood wind damageMicroburst roofsChimney firesCondo association lossesFarm and barn claimsEstimate reviewsNeutral umpire work
Where the money goes missing

Most short claims are not denied. They are just missing lines.

A slope left off the roof diagram. Plaster priced as drywall. Ice-and-water barrier nobody included. Each gap looks small on its own, but together they decide whether the check covers the repair. Vermont Insurance Appraiser starts from the building, not from the carrier’s estimate, and prices what is actually there.

  • Our own measurementsEvery slope, room and wall measured on site rather than borrowed from the carrier’s sketch.
  • Built for an umpireNumbers supported by photos and pricing, because that is what moves an award.
  • Straight answersIf your claim needs a lawyer or just a supplement request, we say so on the first call.
How Vermont Insurance Appraiser works
Line itemCarrierIndependent
Ceiling repair, two rooms$1,840$4,960
Wet insulation removalmissing$1,380
Wall cavity drying & repairmissing$2,150
Ice & water barrier at eavesmissing$1,720
Paint, matching adjoining walls$610$1,290
Total$2,450$11,500

Illustrative figures only, not a real client file. Policy terms decide which items are owed.

Four seasons of claims

Every Vermont season leaves its own kind of damage

The appraisal clause works the same in January and July, but the losses do not. Pick a season to see what a Vermont Insurance Appraiser is usually called about.

Winter claims in Vermont

  • Ice dams
  • Burst pipes
  • Roof collapse
  • Chimney fires

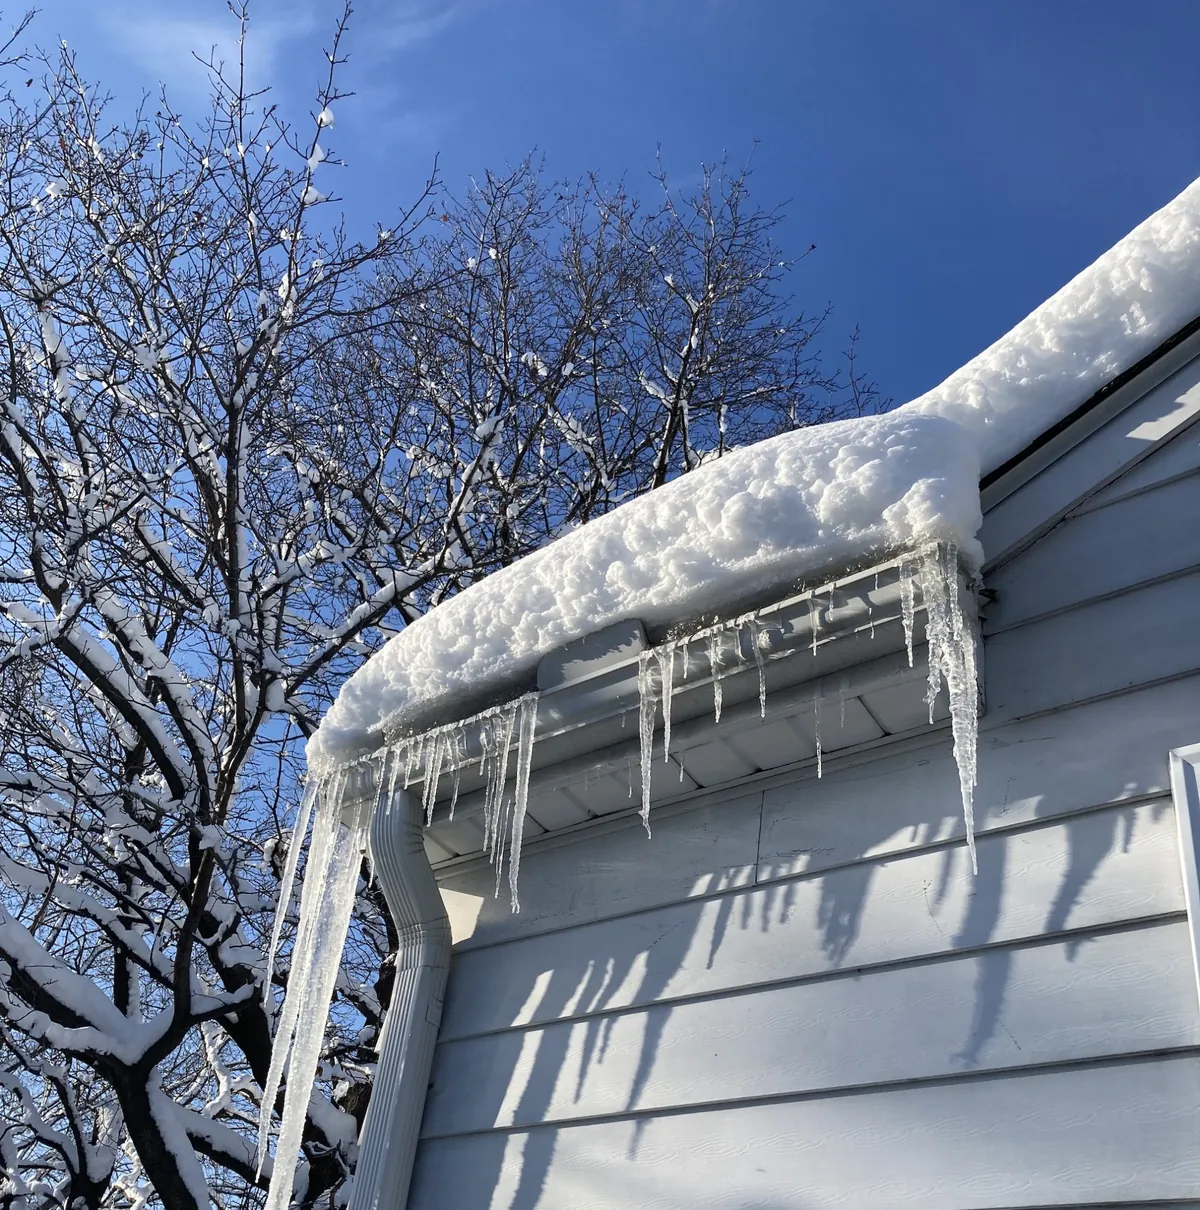
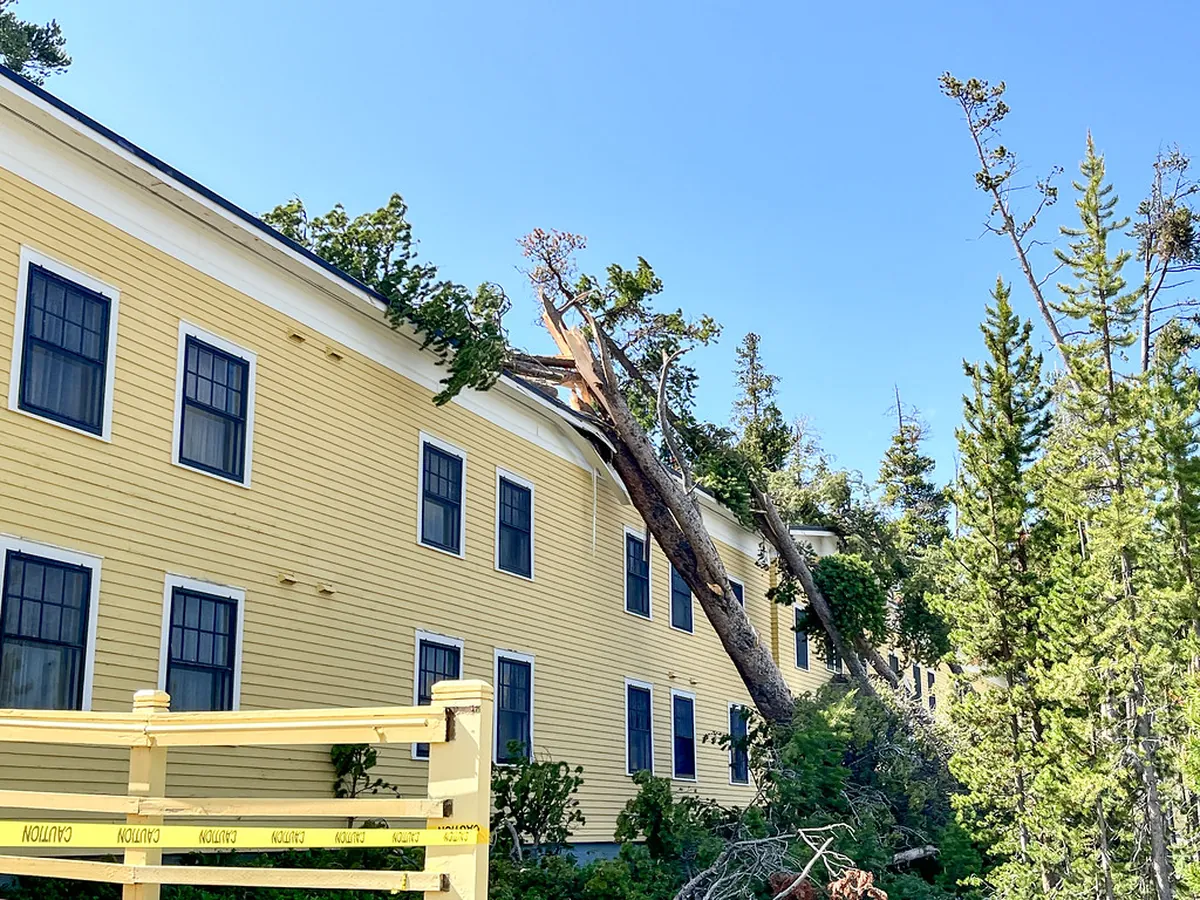
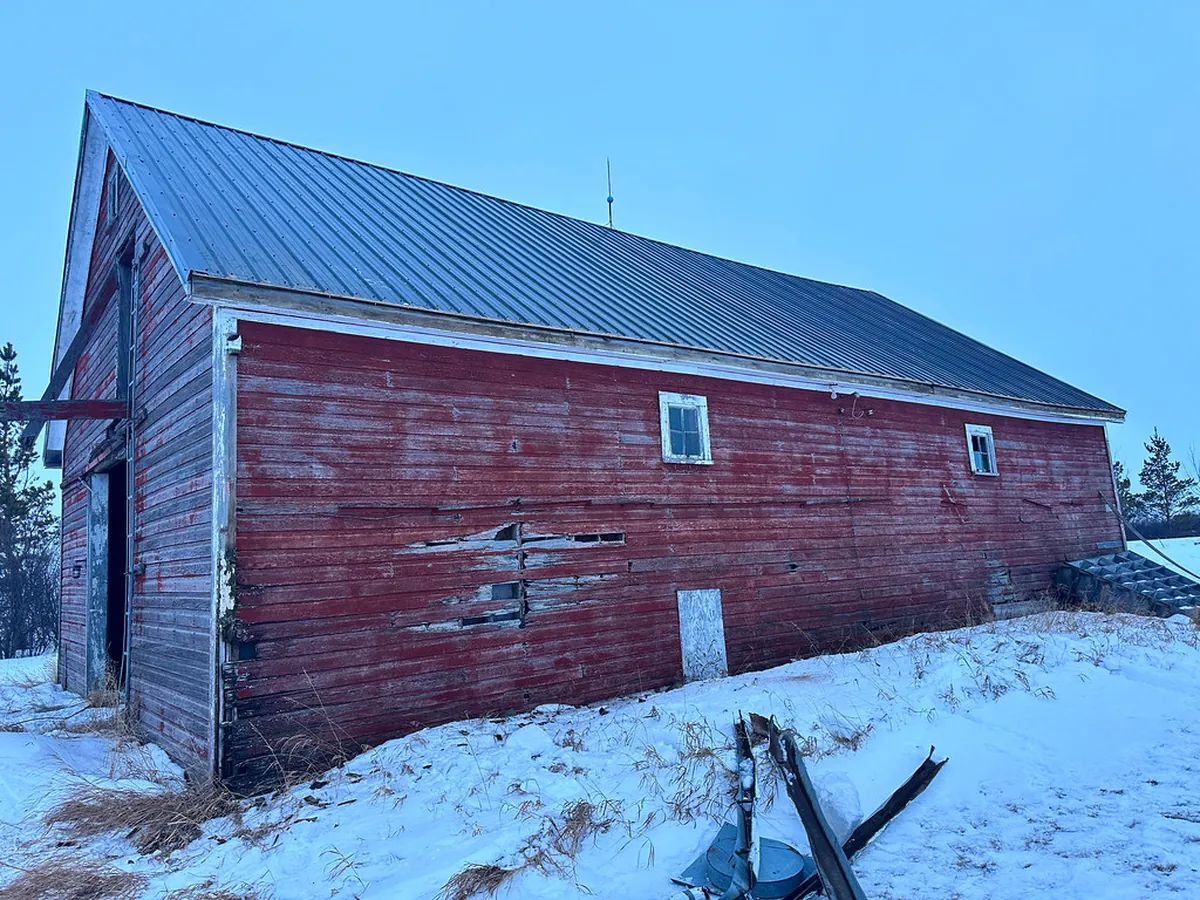
December through March brings the claims Vermont is known for. Meltwater backs up behind ice at the eaves and into ceilings, pipes split during cold snaps, heavy wet snow loads barn and porch roofs, and wood stoves work overtime. A Vermont Insurance Appraiser spends much of the winter following water through walls and checking whether heat conditions in the policy were met.

Appraisal & estimating

Twelve services from Vermont Insurance Appraiser

From a single estimate review to full panel representation or neutral umpire work. Each one is built around a valuation that holds up when someone checks it.

01

Appraisal Clause Representation

We serve as your named appraiser once the appraisal clause is invoked, from inspection through signed award.

02

Homeowner Claim Appraisal

Independent valuation for houses, camps and condos when the carrier’s estimate falls short of the real repair.

03

Commercial & HOA Claim Appraisal

Appraisal for inns, shops, farms, churches, multifamily buildings and condo associations with disputed property losses.

04

Roof & Hail Damage Appraisal

Measured roof scopes for hail, wind and snow damage: slopes, pitch, underlayment, flashing and matching.

05

Wind & Microburst Damage Appraisal

Valuation for straight-line wind, microburst and rare tornado losses, from lifted shingles to structural repair.

06

Tropical Storm Claim Appraisal

Help after the remnants of tropical systems bring wind and rain inland, as Irene and Beryl did.

07

Water Damage Claim Appraisal

Burst pipes, failed fittings, sudden leaks and wind-driven rain: scopes that include drying, demolition and rebuild.

08

Fire & Smoke Claim Appraisal

Structure fires, chimney fires and smoke losses, including soot cleaning, odor control and contents.

09

Ice Dam & Frozen Pipe Appraisal

Vermont’s signature winter claims: meltwater backing up under shingles and pipes that split in a cold snap.

10

Snow Load & Collapse Appraisal

Roof and structural collapse from heavy snow and ice, from sagging rafters to failed barn roofs.

11

Insurance Estimate Review

A line-by-line read of the carrier’s estimate against your property, before you decide on appraisal.

12

Umpire Services

Neutral umpire service for appraisal panels that cannot agree on the amount of loss.

Compare all services

The appraisal clause

From disagreement to signed award

The appraisal paragraph in your policy turns an open-ended argument into a defined process with a binding result on the amount of loss. Here is how Vermont Insurance Appraiser moves a file through it.

Read the full process guide
  1. 1

    Pin down the disagreement

    Appraisal is for one kind of dispute: the carrier accepts that the loss is covered but you disagree on how much it costs.

  2. 2

    Read the appraisal condition

    Find the Appraisal paragraph in the conditions section of your policy.

  3. 3

    Send a written demand

    Either side can usually invoke appraisal in writing.

  4. 4

    Each side names an appraiser

    You choose a competent and impartial appraiser, and so does the carrier.

  5. 5

    The appraisers select an umpire

    The two appraisers try to agree on a neutral umpire, often within 15 days.

  6. 6

    The appraisers work the differences

    The appraisers compare estimates line by line.

Two-number gap check

Is the gap big enough for appraisal?

Type in the two numbers you already have. A large gap is worth a conversation with a Vermont Insurance Appraiser. A small one may close faster with a documented supplement request.

The full claim gap & fee estimator adds appraiser and umpire fees and shows three possible outcomes side by side.

Two-number gap checkNo sign-up
Amount in dispute$0
Gap as % of carrier estimate—

Statewide

One small state, four very different claim regions

Lake wind in the northwest, river floods in the center, deep cold in the Kingdom and Irene’s scars in the south. A Vermont Insurance Appraiser has to price each one with local knowledge.

Champlain Valley & the northwest

Vermont’s most populated region mixes dense older neighborhoods, condos, lake camps and dairy farms. Wind off the lake, ice storms and summer hail are the main weather risks.

Burlington, South Burlington, St. Albans, Middlebury
Central Vermont & the Green Mountains

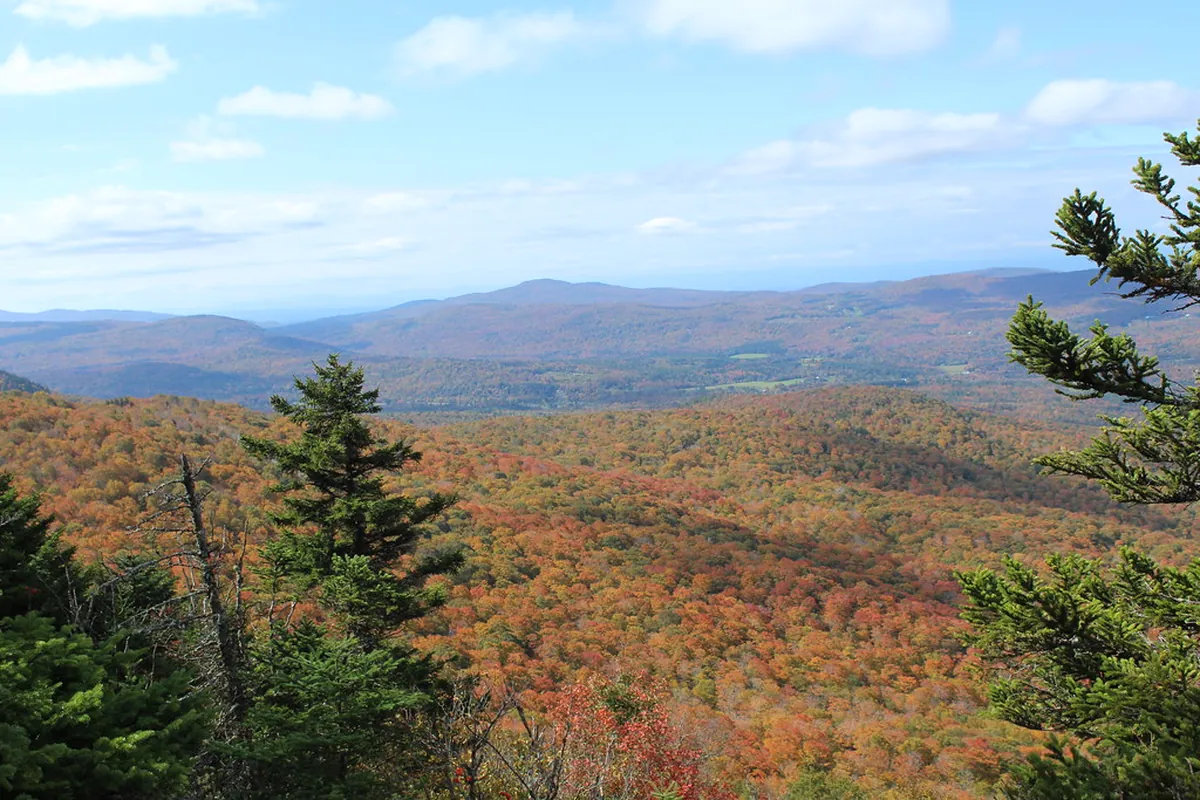
River towns that flooded in 2023 and 2024, plus ski-country homes and condos carrying some of the heaviest snow loads in the state.

Montpelier, Barre, Stowe, Waterbury

The Northeast Kingdom

Long cold winters, remote properties and wood heat. Freeze-ups, snow load and chimney fires lead the claim list, and repair costs reflect the distance.

St. Johnsbury, Lyndon, Newport, Island Pond

Southern Vermont & the eastern river valleys

Irene hit this region hardest in 2011. Historic village homes, hillside lots and river valleys shape both the losses and the repair costs.

Brattleboro, Bennington, Rutland, Hartford

Free & private

Claim tools from Vermont Insurance Appraiser

Check the math before you pick up the phone. Every tool runs in your browser, and nothing you type is stored or sent.

All seven tools, including the roof snow load estimator

Local pages

Towns where Vermont Insurance Appraiser works most

We take claims in every county. These pages cover the towns we hear from most, with their housing, storm history and local claim patterns.

Chittenden County

Burlington

Vermont’s largest city sits on the eastern shore of Lake Champlain, with a housing mix that…

Rutland County

Rutland

The Marble City sits in the Otter Creek valley between the Taconic and Green Mountains, with…

Washington County

Montpelier

The smallest state capital in the country sits where the North Branch meets the Winooski River,…

Washington County

Barre

The Granite City flooded in July 2023 and again in July 2024, when the remnants of Hurricane…

Franklin County

St. Albans

Franklin County’s seat sits above St. Albans Bay near the Canadian border, with a Victorian…

Windham County

Brattleboro

Brattleboro climbs the hills above the big river on Vermont’s eastern border, where Whetstone…

Bennington County

Bennington

Bennington spreads along the Walloomsac River below Mount Anthony, with Old Bennington’s…

See all twelve town pages

Choosing help

Appraiser, public adjuster or attorney?

Each solves a different problem. Picking the right one first saves time and fees, and Vermont Insurance Appraiser will point you elsewhere when appraisal is not the right tool.

QuestionAppraiserPublic adjusterAttorney
Main jobValue the amount of lossPrepare and negotiate the whole claimLegal disputes and lawsuits
Best stageCoverage accepted, amount disputedEarly, from first noticeDenials, bad faith, deadlines
ResultAward signed by two of threeNegotiated settlementSettlement or judgment
Licensed by Vermont DFR?No separate licenseYesLicensed by the Vermont bar
Questions

What people ask a Vermont Insurance Appraiser

Straight answers on how appraisal works, what it costs and when it is the wrong move.

What does a Vermont Insurance Appraiser do?

We value property damage when you and your insurer agree the loss is covered but disagree on the cost. As the appraiser you name, we inspect, write an independent line-item estimate, work the differences with the carrier’s appraiser and, if needed, present open items to a neutral umpire.

Is an appraiser the same as a public adjuster?

No. A public adjuster handles the whole claim for you. An appraiser works inside the policy’s appraisal clause on one question, the amount of loss. We do not give legal advice.

When does it make sense to call?

When coverage has been accepted, you have the carrier’s estimate, and the gap between it and your contractor’s number is meaningful, often more than about 10% or several thousand dollars.

Can appraisal help with a flood claim?

Flood from rising water is usually excluded from homeowners policies. If you also have a flood policy, it has its own appraisal provision and strict deadlines. Covered wind, tree or plumbing damage from the same storm can be appraised under the property policy.

What does it cost?

Each side pays its own appraiser and usually half the umpire. We quote our fee in writing before any work starts, and the first conversation is free.

Do you work in my part of Vermont?

Yes. We work in all 14 counties, from Grand Isle to Windham and from Bennington to Essex.

Field guides

Read before you demand appraisal

Practical guides on ice dams, floods, winter documentation and reading an estimate, written for Vermont owners.

Before you sign off

The best time to check the numbers is before you accept them

A short review now can keep you from settling for a payment that will not cover the work.

Start with a conversation

Talk to Vermont Insurance Appraiser about your claim

Tell us what happened and what the carrier offered. We will review it and give you a straight answer on whether appraisal is worth pursuing, with no pressure and no obligation.

Send your claim details

Free review, no obligation. We usually reply within one business day.

Call nowFree review